Managing your finances is not only about earning, saving, investing, and spending money wisely. It is also about making sure your financial assets can be handled smoothly if something unexpected happens to you. One important part of this planning is choosing a financial nominee.
A nominee is a person you designate to receive or handle certain financial assets after your death, according to the rules applicable to the particular financial product. Nomination can help financial institutions identify the person who should receive the asset or deal with the claim process, potentially making the process more organized for the family.
Many people postpone nomination because they assume it is only relevant to older individuals or people with substantial wealth. In reality, anyone who has a bank account, investment, insurance policy, deposit, or other financial asset may benefit from keeping nominee details updated.
Understanding what a nominee does, what a nominee does not do, and why accurate nomination matters can help you organize your financial affairs more effectively.
What Is a Financial Nominee?
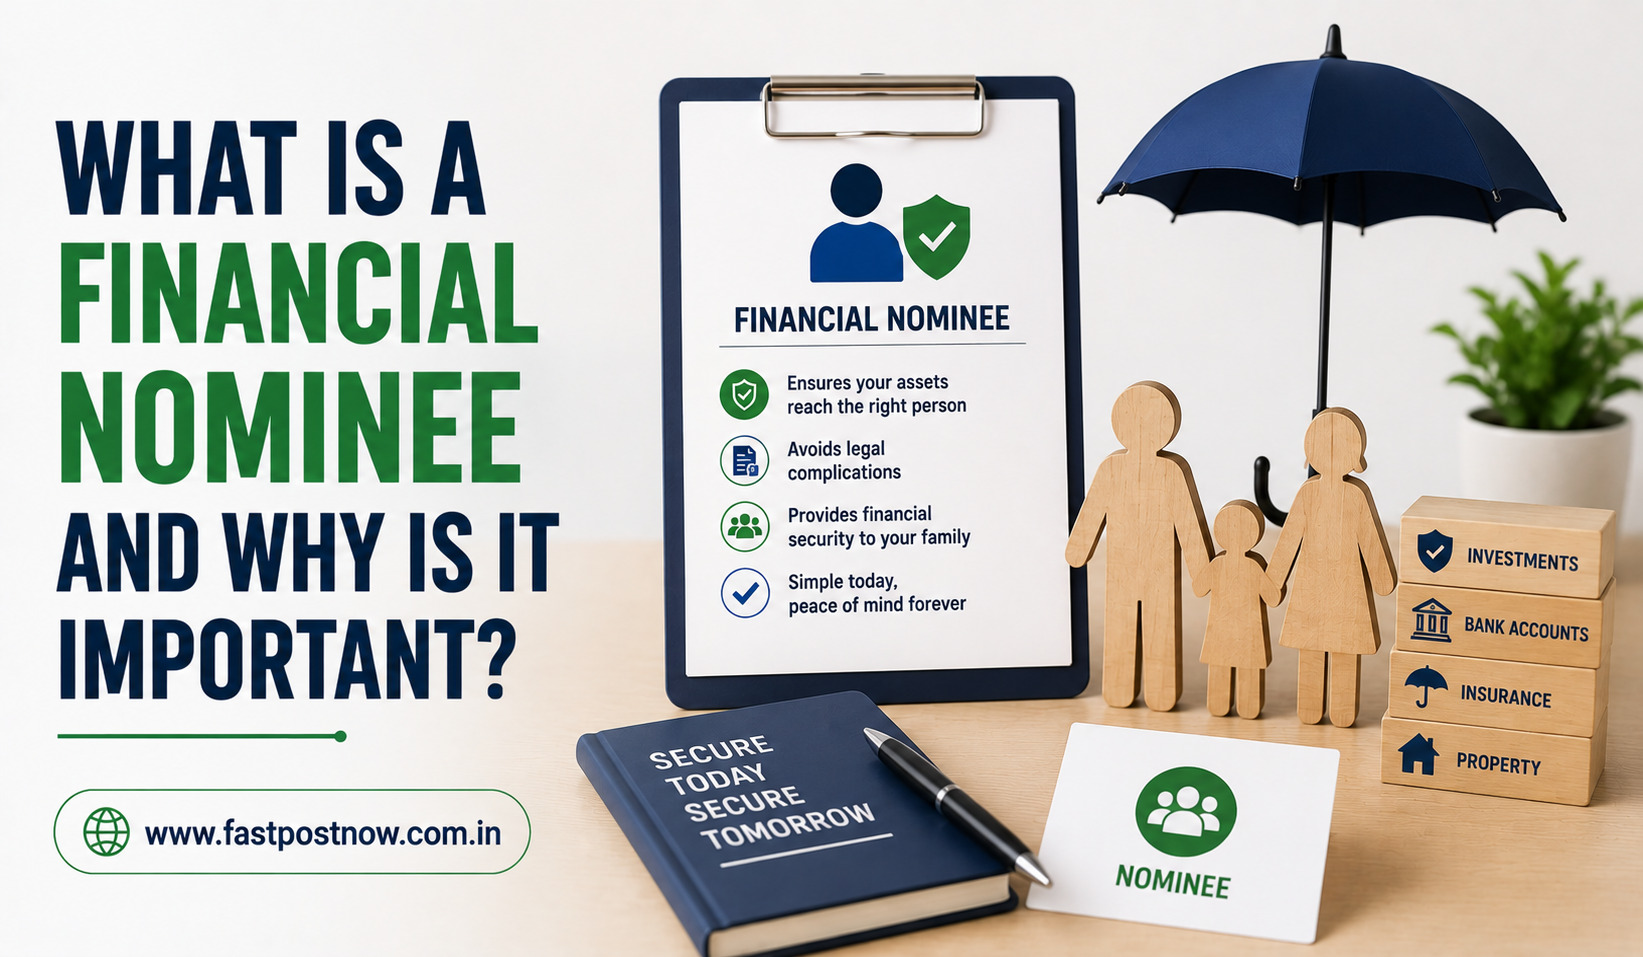
A financial nominee is a person designated by an account holder or policyholder in connection with a financial asset. The nominee is generally identified in the records of the relevant bank, financial institution, insurer, or investment provider.
The purpose of nomination is to provide a recognized person for the institution to deal with when the account holder or investor dies. This can make the administrative process easier because the institution has a designated individual associated with the account.
For example, if you have a savings account and nominate a family member, the bank records that person’s details as your nominee. If you die, the nominee can approach the institution and complete the required process for the relevant funds.
However, nomination does not necessarily mean that the nominee automatically becomes the ultimate owner of every asset. Ownership and succession can depend on the nature of the financial product, applicable laws, beneficiary arrangements, and estate-planning documents.
This distinction is important and is often misunderstood.
Why Is Nomination Important?
Nomination can make the process of dealing with financial assets more straightforward for your family after your death.
Without updated nominee information, relatives may face additional administrative work when identifying accounts, submitting documents, and completing claims. If financial records are spread across different institutions, locating and accessing them can become even more difficult.
A nominee provides financial institutions with a designated point of contact for the relevant asset.
Nomination is particularly useful because people often accumulate financial products over many years. Bank accounts, deposits, insurance policies, investments, retirement-related accounts, and other assets may all have separate records.
Keeping nominee information current helps ensure that your financial arrangements reflect your present circumstances.
Who Can Be a Financial Nominee?
The eligibility of a nominee depends on the financial product and the applicable rules.
In many situations, individuals nominate close family members, such as a spouse, parent, child, or other trusted person. However, the permitted choices and documentation requirements can differ between products.
When selecting a nominee, consider whether the person is someone you trust and whether their details can be accurately recorded.
You should also understand the difference between selecting a nominee and creating a broader estate plan. If your financial situation is complex, simply adding a nominee to individual accounts may not fully address how your assets should ultimately be distributed.
Nominee vs. Legal Heir
One of the most important concepts to understand is that a nominee and a legal heir are not necessarily the same person.
A nominee is generally the person designated in the financial institution’s records to receive or handle the asset according to the applicable nomination process. A legal heir is a person who has rights to the deceased person’s estate under applicable succession laws or other legally recognized arrangements.
For example, you may nominate one family member for a financial account while your estate arrangements provide for assets to be distributed among several people.
The exact legal effect of nomination can vary depending on the financial product and applicable law. Therefore, nomination should not automatically be treated as a substitute for a properly prepared will or broader estate plan.
How Does Financial Nomination Work?
The nomination process generally involves providing the financial institution with information about the person you want to nominate.
Depending on the product, nomination may be completed during account opening or added later. Some institutions allow nomination to be updated through online banking or investment platforms, while others may require a form or additional documentation.
The process may vary, but it commonly involves:
- Providing the nominee’s name and relevant identification details
- Providing the relationship with the nominee, where required
- Confirming or submitting the nomination request
- Keeping the nominee information updated when circumstances change
Always follow the process specified by the institution managing the financial product.
What Information Should You Keep Updated?
Nomination becomes less useful if the information recorded by the financial institution is outdated or incorrect.
When reviewing your financial records, check whether the nominee’s name, relationship, contact information, and other required details are accurate.
It is particularly important to review nomination after major life events such as marriage, divorce, the birth of a child, or the death of an existing nominee.
A person who was appropriate as a nominee several years ago may no longer be the person you want associated with your financial arrangements.
Nomination Across Different Financial Products
Nomination is not limited to bank accounts. Different financial products can have their own nomination facilities and rules.
| Financial Product | Nomination May Be Relevant For |
| Bank accounts | Savings and certain deposit accounts |
| Fixed or recurring deposits | Designating a person for the applicable claim process |
| Insurance | Identifying the person connected with policy benefits |
| Investments | Certain investment accounts and securities |
| Retirement-related accounts | Applicable account or scheme benefits |
| Other financial assets | Depending on the product and governing rules |
The exact rights and procedures can differ considerably. A nomination on one type of financial product should not be assumed to work identically for another.
What Happens If There Is No Nominee?
If a financial account does not have a nominee, the institution may still have a process for settling the deceased person’s assets.
However, the family may need to provide additional documents and evidence to establish the right person to receive or claim the funds. Depending on the circumstances, this can involve succession documents, legal heir documentation, probate-related procedures, or other requirements.
The process can become more complicated when family relationships are unclear or when multiple people have potential claims.
Having a valid nomination does not eliminate every legal or administrative requirement, but it can help simplify the institution’s process.
Can You Change Your Financial Nominee?
In many financial products, nomination can be changed during the account holder’s lifetime by following the institution’s prescribed process.
This flexibility is important because personal circumstances can change.
For example, you may originally nominate a parent and later decide that your spouse should be the nominee. Alternatively, you may need to update the nomination after a nominee’s death.
Whenever your circumstances change, review the nomination records for your financial products rather than assuming that an update to one account automatically changes all your other accounts.
Why Keeping Nominee Details Updated Matters
An outdated nomination can create confusion at exactly the time when your family needs clarity.
Suppose you nominated someone many years ago and have since experienced major changes in your family structure. If you never update the financial records, the institution may still have the old nomination.
This is why nomination should be treated as an ongoing part of financial organization rather than a one-time administrative task.
A useful habit is to review your nominations whenever you conduct an annual review of your finances.
Common Mistakes People Make With Nomination
Many people understand that nomination exists but do not pay enough attention to the details.
One common mistake is leaving the nominee field blank when opening an account. Another is providing incomplete or outdated information.
People may also assume that adding a nominee to one financial account automatically covers all their other assets. It generally does not.
Other common mistakes include:
- Forgetting to update nominations after major family changes
- Assuming a nominee is automatically the final owner of an asset
- Failing to tell a trusted family member where important financial records are maintained
- Assuming that nomination replaces a will in every situation
Avoiding these mistakes can make financial administration considerably easier for your family.
Nomination and Estate Planning
Nomination should ideally be considered alongside broader estate planning.
Estate planning is the process of organizing what happens to your assets and responsibilities in the future. Depending on your circumstances, this may involve a will, property records, insurance arrangements, investment information, and other documents.
A nominee helps financial institutions identify the person designated for the relevant account or benefit. A will can provide broader instructions concerning your estate.
These tools can serve different purposes and should not automatically be treated as interchangeable.
If you have substantial assets, a complicated family situation, jointly owned property, or specific inheritance wishes, obtaining appropriate professional legal advice can help you understand how nomination interacts with succession arrangements.
How to Organize Your Nominee Information
Keeping nomination details organized does not need to be complicated.
Start by creating an inventory of your financial products. Include bank accounts, deposits, investments, insurance policies, retirement-related accounts, and other significant assets.
For each asset, record whether a nominee has been registered and when the nomination was last reviewed.
You can also maintain a secure record of the institutions involved and the relevant account information. Avoid storing sensitive passwords or security credentials in an unsecured document.
The purpose is to make your financial structure easier to understand and locate when necessary.
When Should You Review Your Nominee Details?
There is no need to wait for a specific age or financial milestone to review nomination details.
A periodic review can help identify outdated information. You should pay particular attention after major personal or financial changes.
Consider reviewing your nominations when:
- You get married or divorced.
- A child is born or reaches a relevant age.
- A nominee dies or becomes unsuitable.
- You acquire significant new financial assets.
An annual financial review can also be a convenient time to check nomination records.
Frequently Asked Questions
Is a financial nominee the same as a legal heir?
No. A nominee and a legal heir can be different people. A nominee is generally the person designated with the financial institution for the relevant account or benefit, while legal-heir rights depend on applicable succession laws and other legal arrangements.
Can I have different nominees for different financial products?
Yes, nomination is generally maintained separately for individual financial products, subject to the rules applicable to each product. You should review each account or investment individually.
Can I change my nominee later?
In many cases, yes. Financial institutions generally have procedures for changing nomination details. The exact process depends on the product and institution.
Does having a nominee eliminate the need for a will?
Not necessarily. Nomination and a will can serve different purposes. A nominee may help with the institution’s claim or transfer process, while a will can provide broader instructions concerning your estate.
What happens if my nominee dies before me?
You should review and update the nomination according to the financial institution’s procedure. Leaving outdated nominee information can create unnecessary complications later.
Final Thoughts
Choosing a financial nominee is a simple but important part of organizing your financial affairs. It gives financial institutions a designated person to deal with when a financial asset holder dies and can help make the administrative process more manageable for the family.
However, nomination should not be confused with ownership or comprehensive estate planning. The legal effect of a nomination can depend on the type of financial product and applicable laws.
The most effective approach is to register appropriate nominees across your financial products, keep their information accurate, and review those details whenever your personal circumstances change. It is equally important to maintain organized financial records so that your family can identify your accounts and assets when needed.
Good financial planning is not only about building wealth during your lifetime. It is also about making your financial affairs easier to understand and manage when someone else may eventually need to handle them. A properly maintained nomination structure can be one useful part of that preparation.