Understanding your financial position is one of the most useful habits you can develop when managing money. While income tells you how much you earn and a budget shows where your money goes, your personal net worth gives you a broader picture of what you actually own compared with what you owe.
Calculating net worth may sound like something reserved for wealthy investors or business owners, but it is useful at almost every stage of life. Whether you are paying off debt, building an emergency fund, saving for a home, investing for retirement, or simply trying to become more financially organized, knowing your net worth can help you measure progress.
You simply identify your assets, add their current values, identify your liabilities, and subtract what you owe from what you own.
What Is Personal Net Worth?
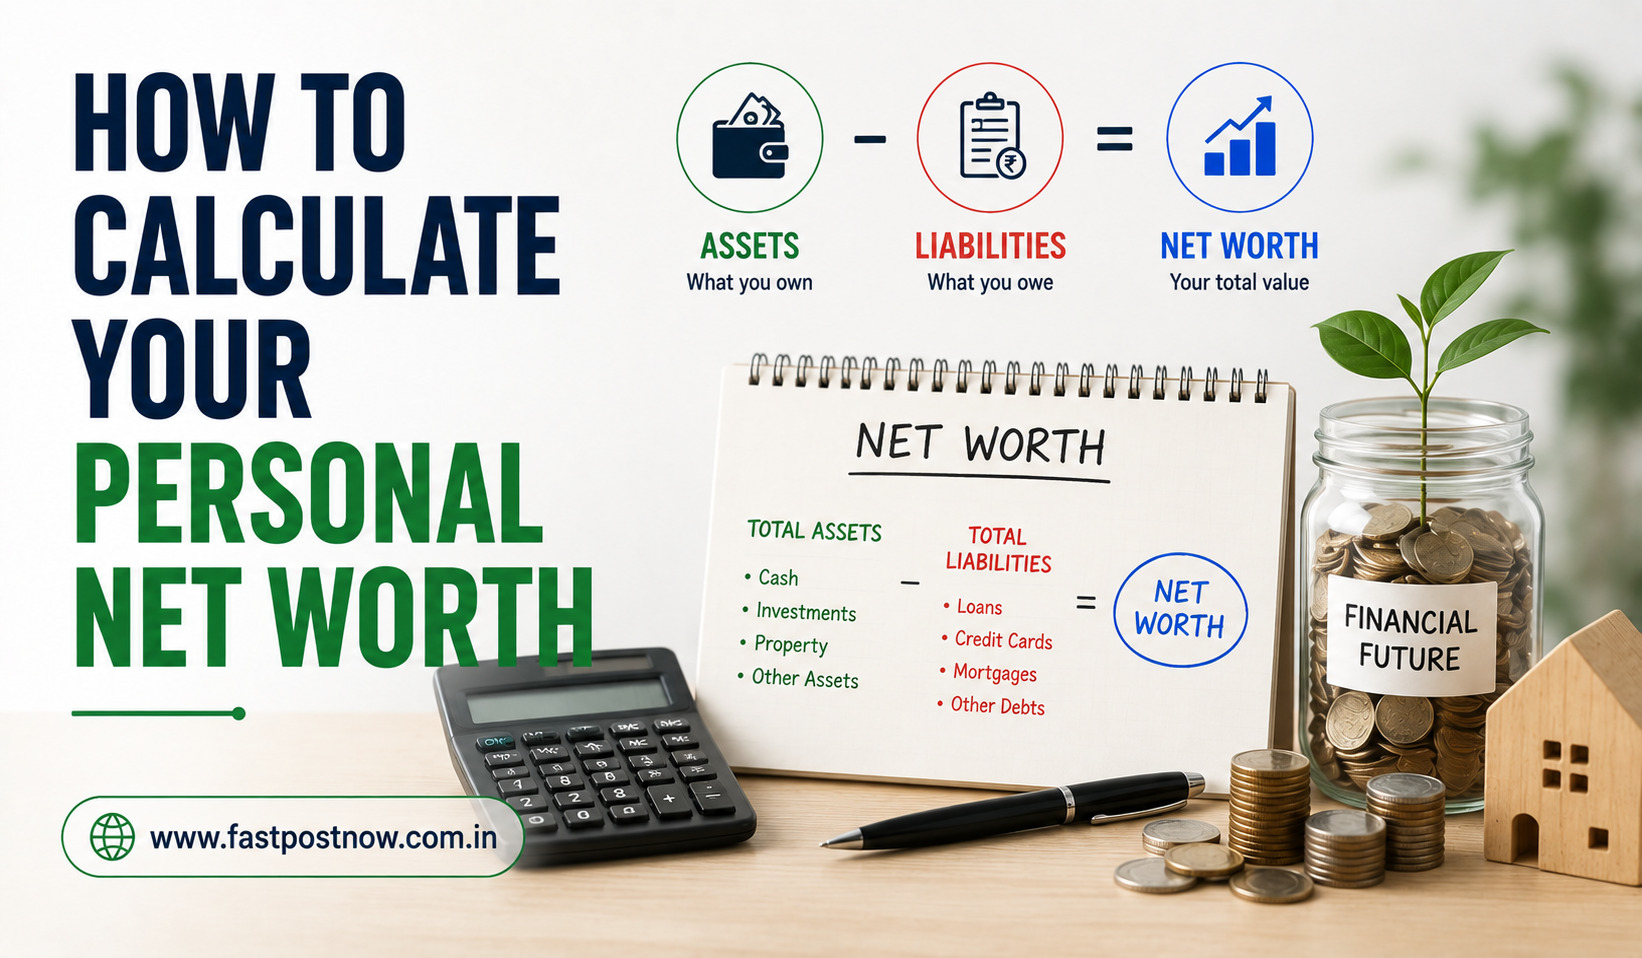
Personal net worth is the total value of your assets minus the total value of your liabilities. In simple terms, it represents your financial position at a specific point in time.
The basic formula is:
Net Worth = Total Assets − Total Liabilities
These can include money in bank accounts, investments, property, vehicles, and certain valuable personal possessions. Liabilities are financial obligations you still need to repay, such as credit card balances, personal loans, student loans, mortgages, or vehicle loans.
For example, imagine you have ₹8 lakh in savings and investments, a car worth ₹5 lakh, and other assets worth ₹2 lakh. Your total assets would be ₹15 lakh. If you have ₹6 lakh in outstanding loans and other debts, your liabilities would be ₹6 lakh. Your net worth would therefore be ₹9 lakh.
Net worth is not the same as your bank balance. Someone may have substantial savings but also carry significant debt. Another person might have relatively little cash but own a valuable property with a small remaining mortgage. Net worth considers both sides of the financial picture.
Why Should You Calculate Your Net Worth?
Your net worth provides a financial snapshot that can help you make better decisions. Looking only at income can sometimes create a misleading impression of financial health. A high salary does not automatically mean someone has strong finances if spending and debt are also high.
Tracking net worth over time gives you another way to understand whether your financial decisions are moving you forward. If your investments grow, debts decrease, and savings increase, your net worth may rise even if your income stays the same.
It can also help you identify areas that deserve attention. If most of your wealth is tied up in one asset, you may want to consider diversification. If your liabilities are growing faster than your assets, reducing debt may become a priority.
For this reason, calculating net worth can be particularly useful when setting long-term financial goals.
Step 1: List All Your Assets
The first step is to determine everything you own that has meaningful financial value. Use current estimated values rather than what you originally paid.
Common assets include:
- Cash and bank account balances
- Stocks, mutual funds, bonds, and retirement investments
- Real estate and land
- Vehicles
- Business ownership interests
- Valuable personal property
Do not worry about making the first calculation perfect. The objective is to create a realistic snapshot. Bank balances are usually easy to determine, while the value of a home, vehicle, or business may require an estimate.
Cash and Savings
Include the current balances of your savings accounts, checking accounts, fixed deposits, recurring deposits, and other cash-equivalent holdings. If you have money spread across several accounts, add each balance together.
Avoid counting your monthly salary twice. Only money that is actually held in an account or another asset should be included.
Investments
Investments can form an important part of net worth. Include the current market value of stocks, mutual funds, exchange-traded funds, bonds, retirement accounts, and other investments.
Use their current value rather than the amount you originally invested. Markets fluctuate, so your investment value may be different from the amount you contributed.
Property and Vehicles
If you own a house, apartment, land, or another property, estimate its current market value. You can use recent comparable property prices or a reliable valuation as a starting point.
Vehicles should also be valued according to what they could reasonably sell for today, rather than their original purchase price. Because vehicles generally depreciate, using the purchase price can significantly overstate your assets.
Step 2: Add Up Your Liabilities
Once you have identified your assets, list everything you currently owe. Liabilities should reflect outstanding balances, not the original amount borrowed.
Typical liabilities may include:
- Credit card balances
- Home loans or mortgages
- Car or vehicle loans
- Personal loans
- Student or education loans
- Business-related personal debt
- Other outstanding financial obligations
For example, if you originally borrowed ₹10 lakh for a vehicle but have already repaid ₹4 lakh of principal, the liability you consider is the remaining balance, not the original ₹10 lakh.
Credit card debt deserves particular attention because interest charges can make it expensive to carry a balance. Including the current outstanding amount in your net-worth calculation can also make the financial impact of high-interest debt more visible.
Step 3: Calculate Your Net Worth
After adding your assets and liabilities, the final calculation is simple.
Suppose your financial position looks like this:
| Category | Amount |
| Savings and cash | ₹4,00,000 |
| Investments | ₹7,00,000 |
| Property | ₹25,00,000 |
| Vehicle and other assets | ₹4,00,000 |
| Total Assets | ₹40,00,000 |
| Home loan | ₹18,00,000 |
| Personal and vehicle loans | ₹3,00,000 |
| Credit card debt | ₹1,00,000 |
| Total Liabilities | ₹22,00,000 |
| Net Worth | ₹18,00,000 |
Using the formula:
₹40,00,000 − ₹22,00,000 = ₹18,00,000
This means your estimated personal net worth is ₹18 lakh.
What If Your Net Worth Is Negative?
A negative net worth does not necessarily mean you are failing financially. It simply means your liabilities currently exceed the value of your assets.
This situation can occur when someone has recently purchased a home, taken education loans, financed a vehicle, or accumulated other debt. Younger adults may also have limited assets while carrying significant student or personal loans.
The important point is to understand why your net worth is negative and whether it is improving.
For example, paying down a loan reduces your liabilities. Building savings increases your assets. Investing consistently can potentially increase assets over the long term, although investments can also lose value and should not be treated as guaranteed growth.
Instead of becoming discouraged by a negative number, use it as a baseline. Your goal can be to gradually move the figure upward.
How Often Should You Calculate Net Worth?
There is no universal rule, but reviewing your net worth every three to six months can provide a useful balance. Checking it too frequently may encourage you to focus on short-term market movements rather than long-term progress.
A quarterly review can help you see whether your savings, investments, debt repayment, and major financial decisions are having the intended effect.
It is also useful to calculate net worth whenever you experience a major financial change, such as purchasing property, receiving an inheritance, paying off a major loan, changing investment strategies, or starting or selling a business.
How to Increase Your Personal Net Worth
Increasing net worth generally involves growing valuable assets, reducing liabilities, or doing both at the same time. The most appropriate approach depends on your income, financial goals, debt obligations, and risk tolerance.
One practical strategy is to create a sustainable gap between your income and expenses. Money that is consistently saved or invested can gradually increase your assets.
Another approach is to focus on expensive debt. Paying down high-interest balances can strengthen your financial position because the outstanding liability decreases while you avoid additional interest costs.
Building investments can also contribute to long-term wealth creation. Diversified investments appropriate to your financial goals and risk tolerance may provide growth over time, although all market investments carry some level of risk.
Most importantly, focus on sustainable progress rather than dramatic short-term changes.
Common Mistakes When Calculating Net Worth
A net-worth calculation is only useful when the information behind it is reasonably accurate. One common mistake is using the original purchase price of assets instead of their current estimated value.
Another mistake is forgetting smaller liabilities. A credit card balance or personal loan may seem insignificant compared with a mortgage, but excluding several smaller debts can distort the overall calculation.
Some people also overvalue personal possessions. Furniture, electronics, clothing, and other everyday items may have much lower resale values than their original purchase prices. Unless an item has meaningful resale value, it may not need to be included.
Finally, avoid treating net worth as a measure of personal success. It is a financial measurement, not a measure of intelligence, happiness, career achievement, or quality of life.
How to Track Your Net Worth Over Time
Once you have calculated your starting figure, keep a simple record containing the date, total assets, total liabilities, and net worth. You can use a spreadsheet, financial app, or basic document.
Instead, look for trends. If your net worth is gradually increasing over several years, your overall financial strategy may be working.
When reviewing changes, consider what caused them. A rise may come from increased savings, investment gains, property appreciation, or debt repayment. A decline may result from market losses, major purchases, new borrowing, or unexpected expenses.
Understanding the reason behind the change is often more valuable than the number itself.
Net Worth vs. Income: What’s the Difference?
Income is the money you receive from employment, business activities, investments, rental income, or other sources. Net worth measures the relationship between what you own and what you owe.
A person earning ₹20 lakh per year could have a lower net worth than someone earning ₹10 lakh if the first person spends heavily and carries substantial debt while the second saves and invests consistently.
This distinction is important because income provides financial capacity, while net worth reflects accumulated financial resources.
Frequently Asked Questions About Personal Net Worth
Is a house included in net worth?
Yes. If you own a house or other property, its estimated current value can be included among your assets. However, any remaining mortgage or home loan should be included as a liability.
Should Your Car Be Included in Your Net Worth Calculation?
Yes, if the vehicle has meaningful resale value. Use a realistic estimate of its current market value rather than its original purchase price. If you still have a vehicle loan, include the outstanding loan balance among your liabilities.
Should retirement savings be included?
Generally, yes. Retirement accounts and long-term investments are assets and can be included in your net-worth calculation. Depending on the account and jurisdiction, taxes or withdrawal restrictions may affect the amount you could actually access.
How often should I check my net worth?
For most people, every three to six months is sufficient. A quarterly review can help you identify long-term trends without encouraging unnecessary reactions to short-term market fluctuations.
What is a good net worth for my age?
There is no single number that represents a good net worth for everyone. Income, location, family responsibilities, career stage, debt, lifestyle, and financial goals all influence what is appropriate. Comparing your current position with your own previous results is often more useful than comparing yourself with others.
Can net worth decrease even when I am saving money?
Yes. Investment values can fall, property values can change, or new debt can temporarily offset your savings. Net worth is a snapshot and can move up or down. What matters most is the longer-term direction and the reasons behind the changes.
Final Thoughts
Calculating your personal net worth is one of the simplest ways to understand your overall financial position. The process requires only two major steps: determining what you own and determining what you owe. Subtracting your liabilities from your assets gives you a starting point from which you can measure future progress.
Your net worth does not need to be perfect, and it does not need to be compared with anyone else’s. What matters is using it as a practical financial checkpoint. By reviewing it periodically, reducing unnecessary debt, building savings, and investing according to your long-term goals, you can create a clearer picture of where your finances are heading.
Think of your first calculation as a baseline rather than a final score. Over time, the changes in that number can show you whether your financial decisions are helping you build greater financial stability and long-term wealth.

